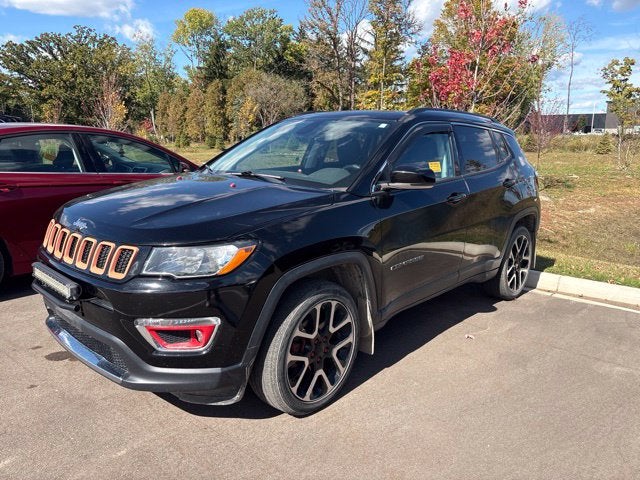
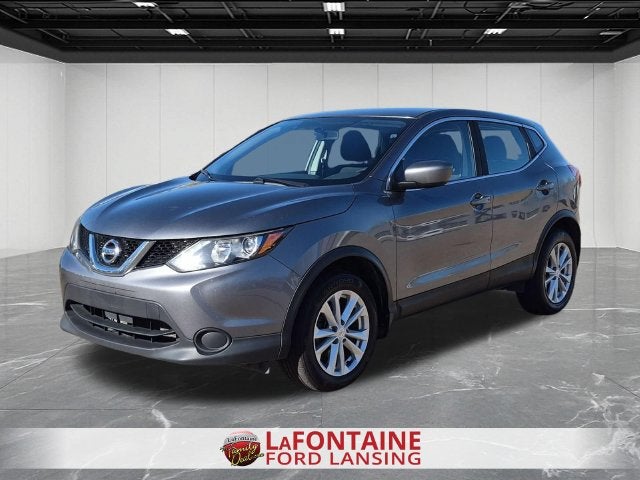
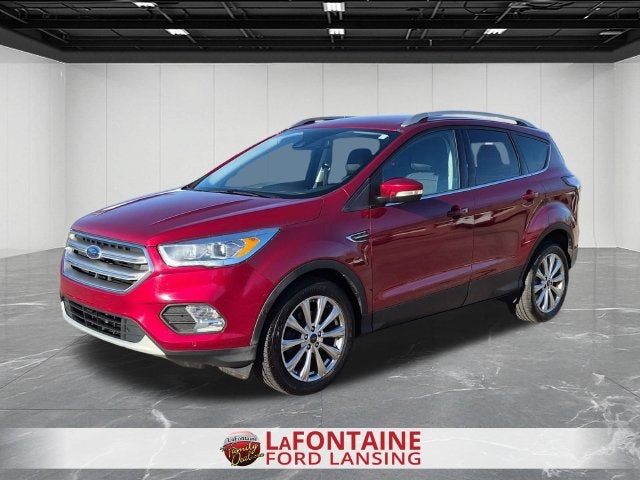
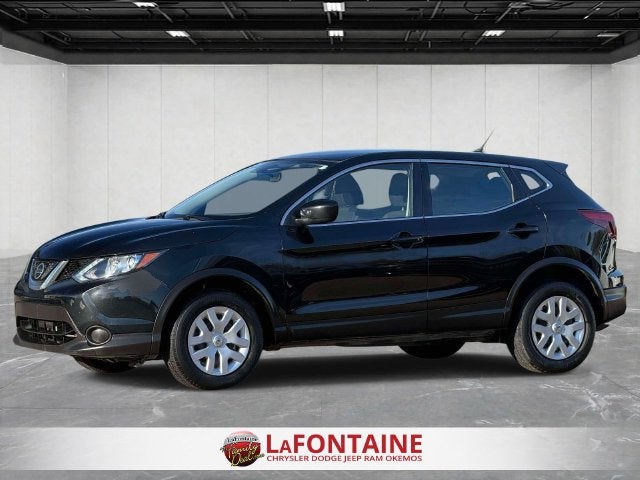
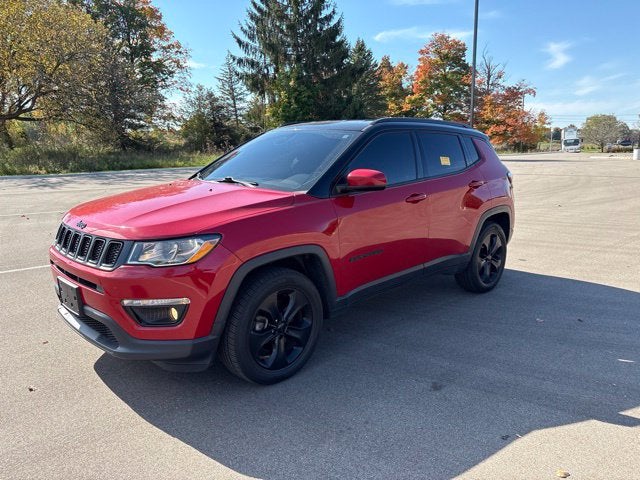
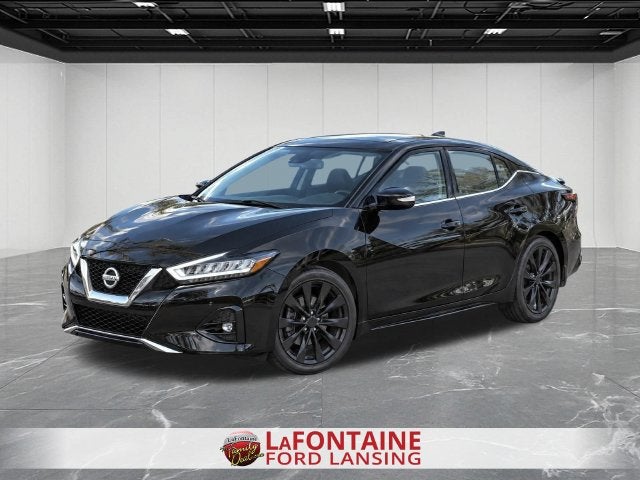
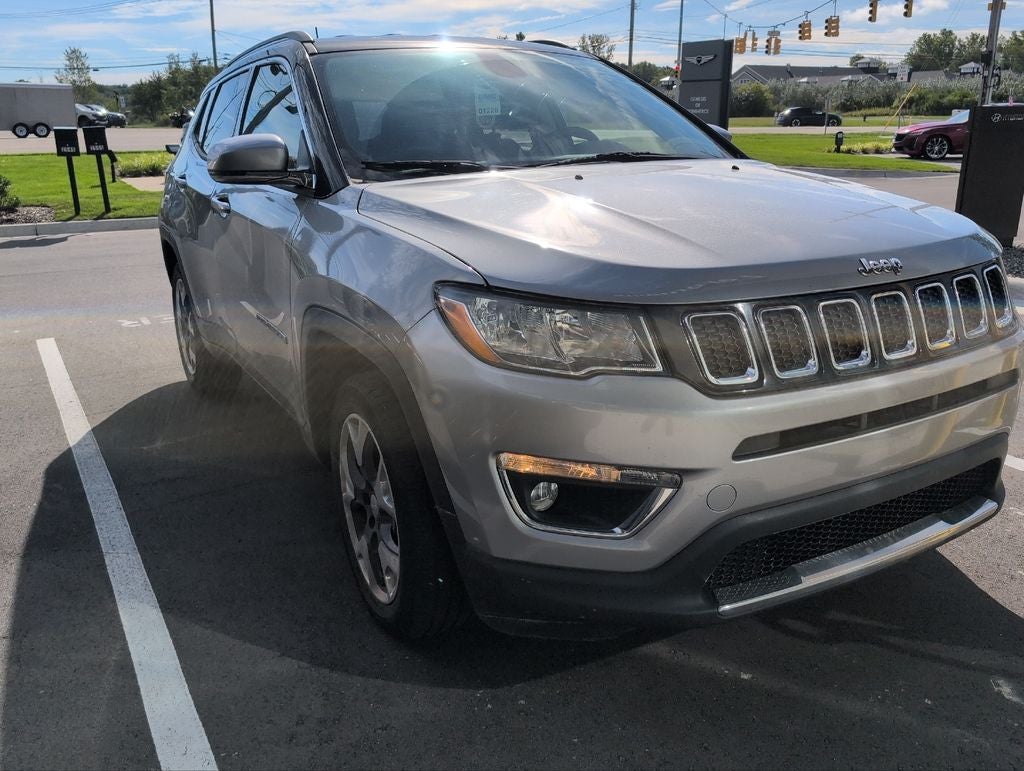
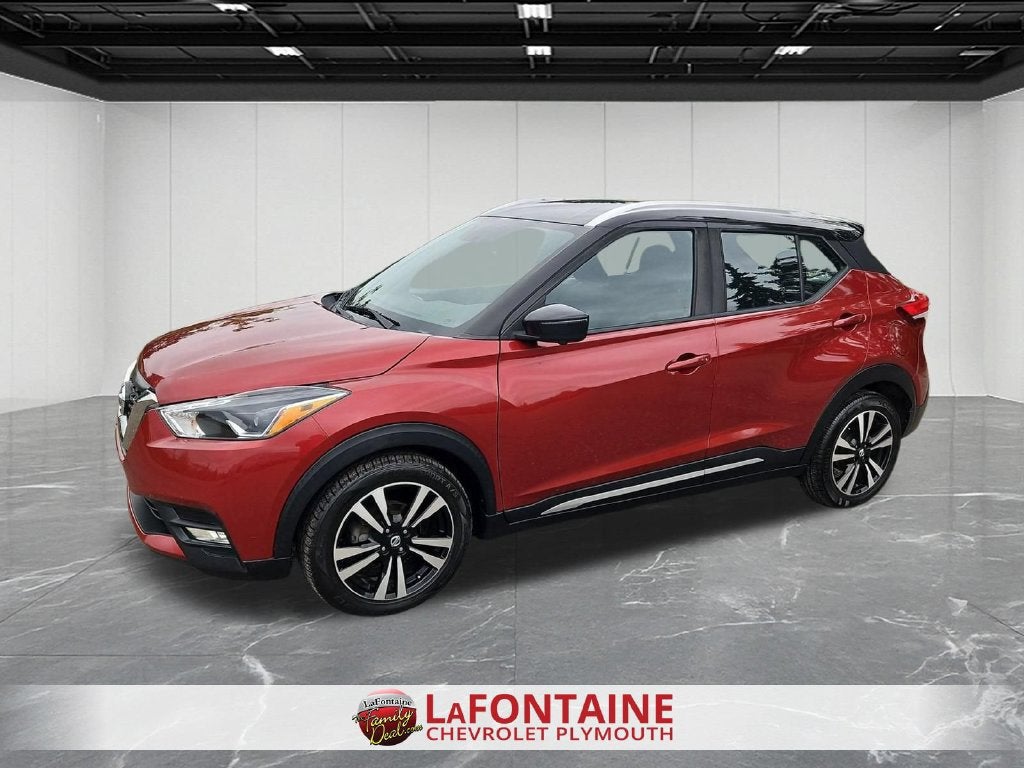
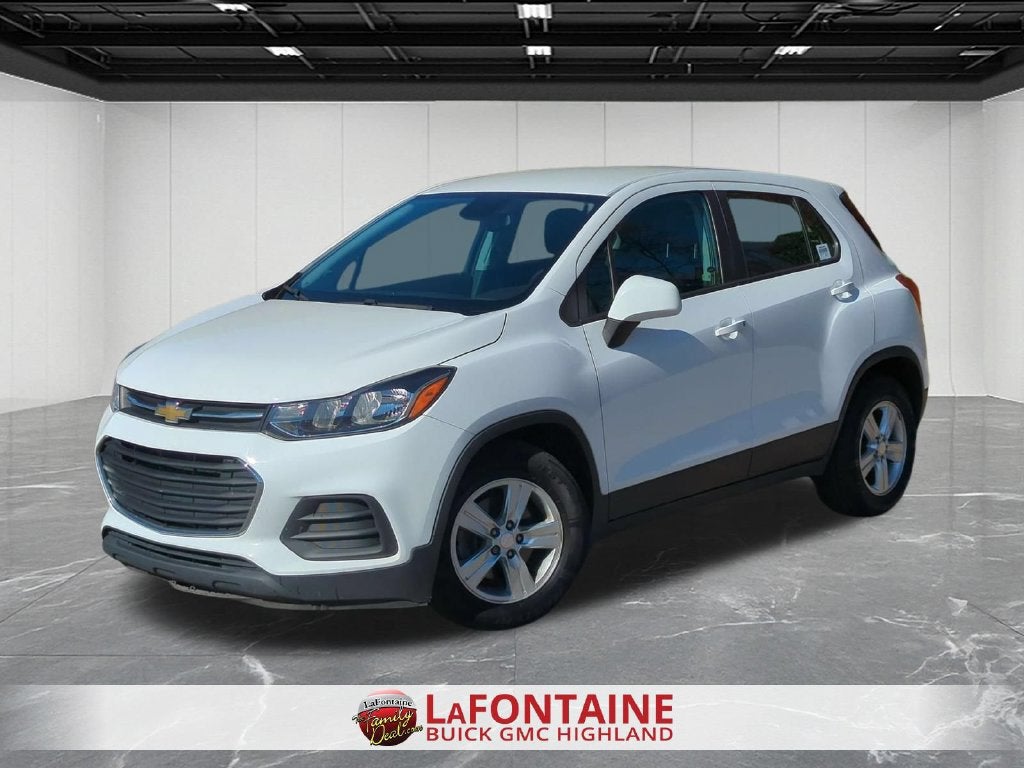
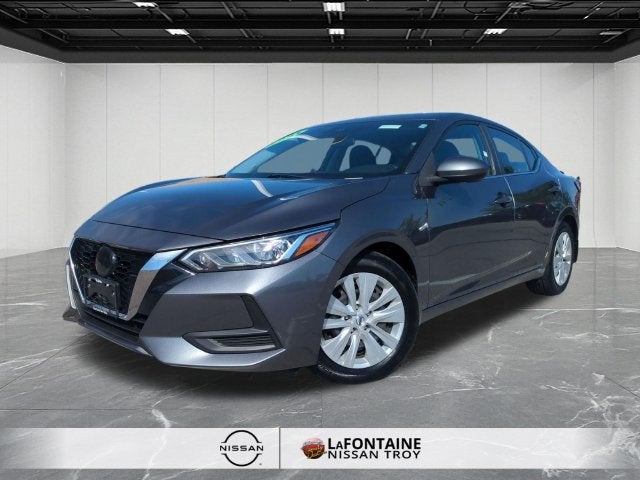
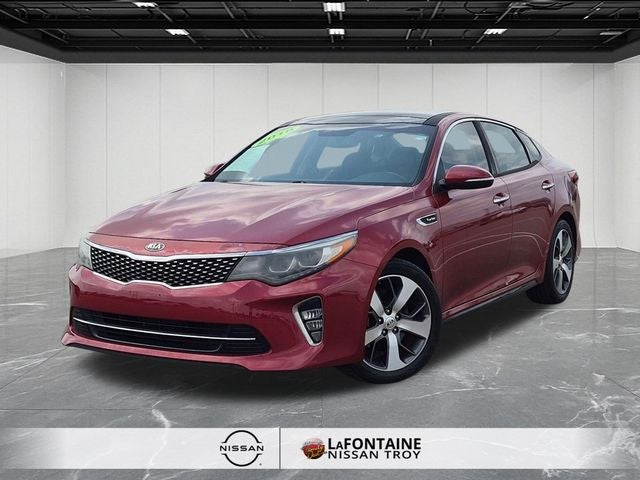
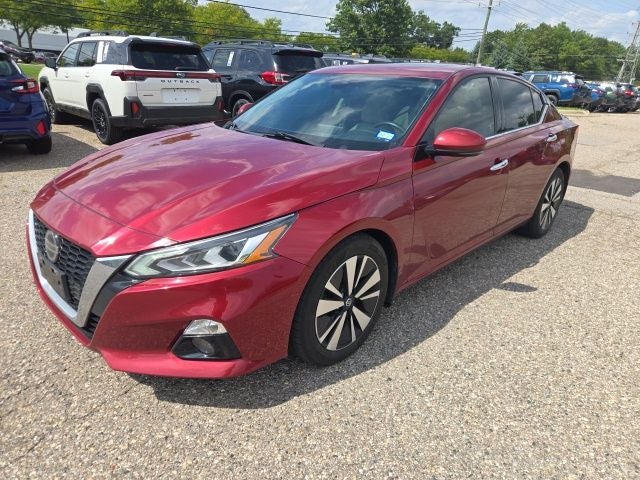
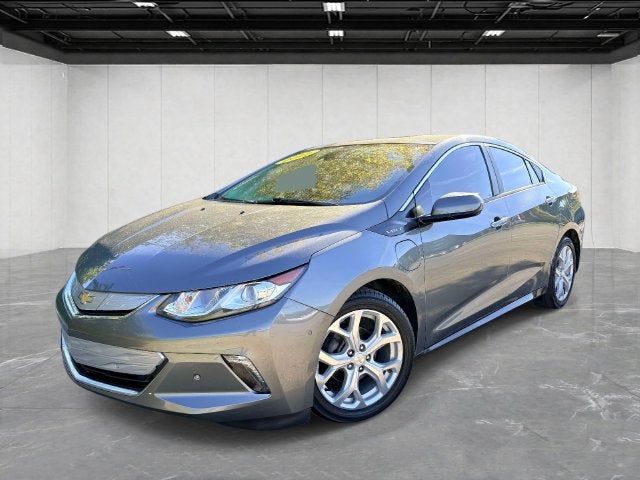
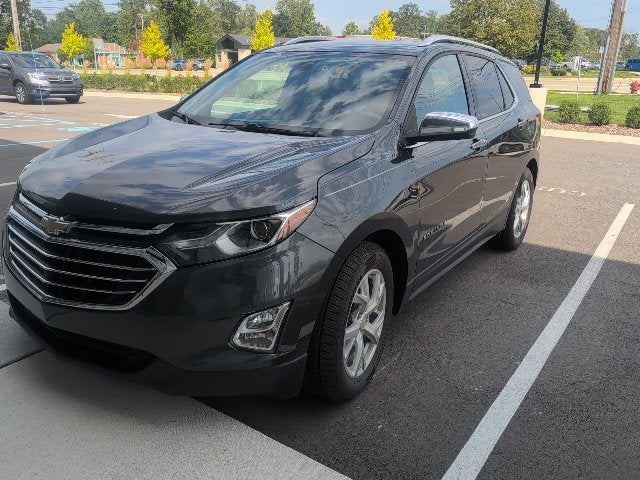
Rebuilding credit? Then the car matters as much as the credit. Before a lender looks at you, it looks at the car: how old it is, how many miles it has, and whether the price sits comfortably under what the car is actually worth.
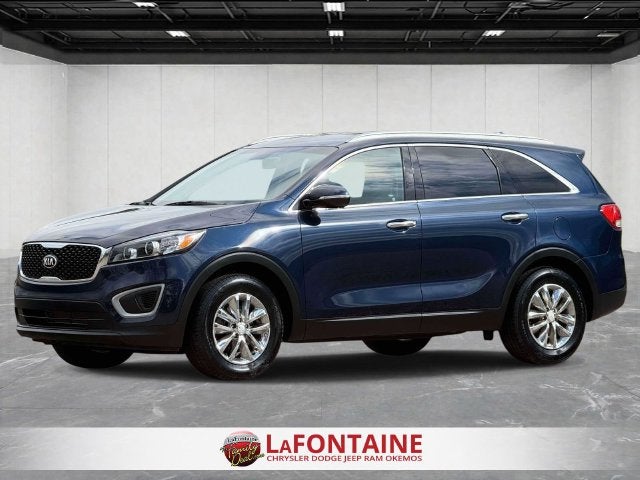
This list is built on exactly that. The main list keeps to the shape lenders like best — 2017 or newer, under 120,000 miles, under $15,000 — and sorts it by Top Quality: the gentlest miles-per-year first, then newer cars, then the best price position against market value. These are the cars that give an application its strongest start.
- Age: every car in the main list is under 10 years old. Older cars are harder to finance, full stop — they’re in the widened list below if you want them.
- Miles: under 120,000, and ranked by miles per year of life — a gently driven 2018 beats a run-hard 2020.
- Price vs. value: where a car carries a MarketCheck market value and our price sits under it, the card says so. A loan that starts under the car’s value is an easier loan for a lender to approve.
- Money down helps: it doesn’t have to be a fortune. Every dollar down shrinks the loan against the car’s value, and a trade-in counts toward it. Jacob will show you what different down payments actually change before you commit to anything.
Straight talk: nobody can promise a lender’s decision, and we won’t. What Jacob can promise is the strongest cars for the application, real numbers up front, and a real answer — the same day in most cases.
Financing, made easy
Yes — we can definitely make financing easy. Straight answers up front, paperwork started before you arrive, and a real answer the same day in most cases. What we'll never do is promise an approval before the lender sees the full picture.
Can I get financed with challenged credit?
Very often, yes. GM Financial works with many credit histories — including people who are rebuilding. Jacob can't promise an approval (nobody honestly can, sight unseen), but you'll get a real answer fast, with no pressure either way.
How much down do I need?
It depends on the car and the approval — some buyers get in with $0 down. More down means a lower monthly payment and an easier approval, and a trade-in can count toward it. Jacob will lay out the real options for the car you pick.
Can I use a co-signer?
Yes. A co-signer with stronger credit can help on both approval and rate, and it's a common route for first-time and rebuilding buyers.
Can I trade in my current car?
Yes — and your trade's value can go straight toward your down payment. Tell Jacob what you're driving when you reserve, and he'll have a real number ready.
What should I bring?
A driver's license, proof of income (a recent pay stub is perfect), and proof of residence (a utility bill or lease). That's enough to get a real answer in most cases.
How fast will I know?
In most cases, the same day. Reserve the car, Jacob starts the paperwork before you arrive, and you're not sitting in a finance office for hours finding out.